
The credit note has spent three months folded into quarters in a wallet, between a loyalty card and an unclaimed dry-cleaning ticket. Thirty-five pounds back on a pair of jeans too tight across the hips, turned into a printed promise. Does that promise still stand when the shutters come down for good?
A credit note is not money you own
Retrace the steps. You take back a coat, the shop accepts it, keeps your payment and hands you a piece of paper: credit note for £89. At that moment, the money has already changed hands. What you are holding is not a sum set aside; it is the retailer's acknowledgement of debt to you — except the debtor here is a shop, not a bank.
One consequence is easy to forget when you are standing in front of a rail: your credit note can almost never be exchanged for cash. It only lives if the retailer can turn it into goods. While the doors are open and deliveries are arriving, all is well. The day cash flow is squeezed, your credit note sits among the unsecured claims, often behind employees and certain preferential creditors. A place you did not choose.
And that is where the amount matters. A return credit note often comes to a few tens of pounds, sometimes £100 to £150 when it is a wool piece or a coat. Suffice to say most of us are carrying a small forgotten credit note in a bag, not a war chest. All the more reason not to let it sit there.
Taken over or wound up: two scenarios, two responses
First case: a takeover. A buyer takes over all or part of the chain, usually as part of a sale of the business. Good news for staff and stores, less good for your credit note: the buyer is not obliged to honour credit notes issued before it took over. Some do it to avoid alienating customers and keep the customer database; others negotiate a partial conversion (a £50 credit note is worth £25 on the new stock); others refuse outright and put up a notice at the entrance. No automatic rule, then — and little to negotiate on your own with a customer service team under new ownership.
Second case: liquidation. Stock goes, the windows stay empty, the retailer stops trading. Your credit note can no longer be converted: no shop, no goods to exchange. The debt still exists: the company may remain in existence for the duration of the process and holders can submit their claim, but there is often no asset behind it, and repayment is unlikely. It can feel like a bad trick, when it is simply the mechanics of a debt that is hard to recover.
The warning signs that should make you spend it
A credit note in trouble does not announce itself by recorded delivery. You sense it. Rails looking sparse and not being restocked, heavy discounts outside sale season, deliveries that drag, returns refused or routinely turned into credit (always credit, never a refund), a website stuck in prolonged maintenance, store closures announced one after another: these are the kind of small stones that, lined up, tell you cash flow is tight.
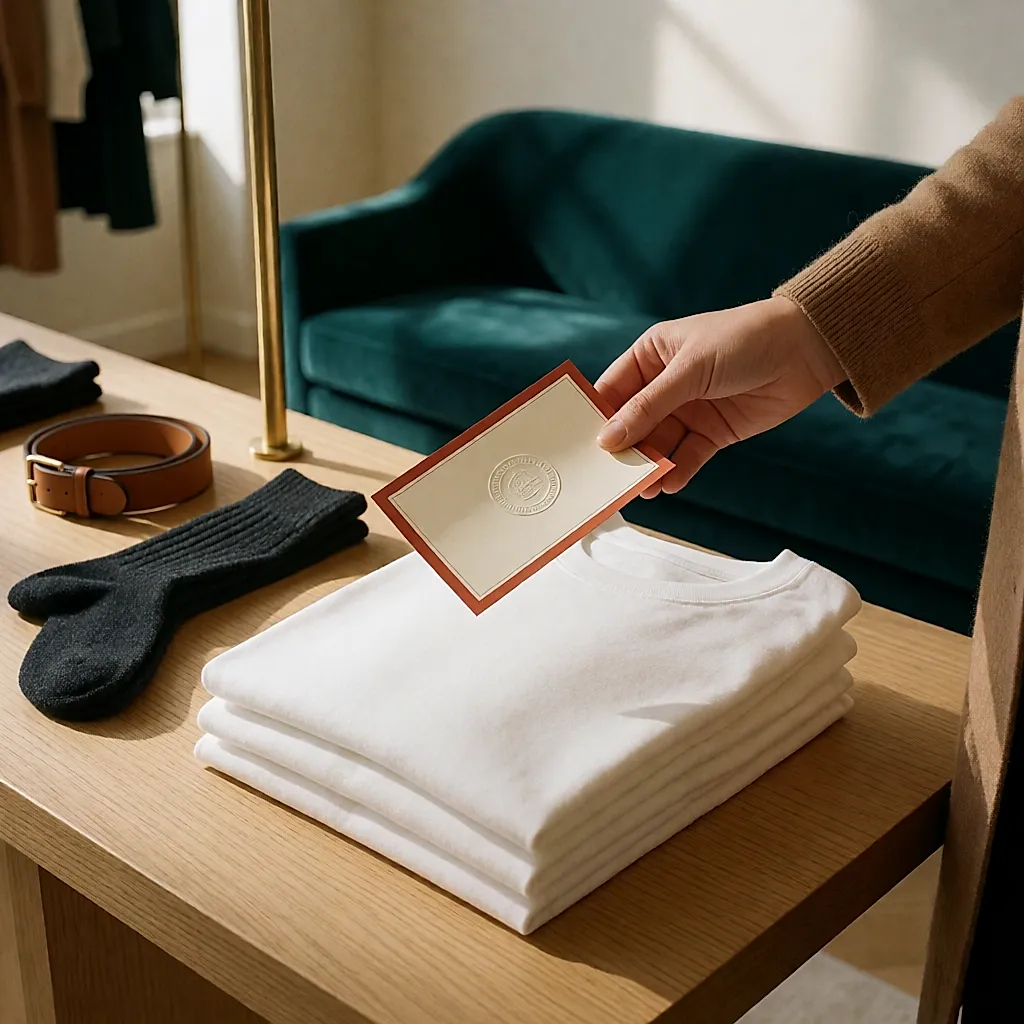
The reflex in that situation comes down to one sentence: spend the credit note before you need to, not after. You accept leaving with a decent piece rather than waiting for the perfect piece that will never come. Prioritise basics that earn their place — a cotton T-shirt, a belt, socks — rather than a made-to-measure order. And above all, do not ask for a credit note for a large amount when a refund is possible: better a slower refund than a fragile credit note. It is less elegant than a jacket with an impeccable cut, but much safer.
Before you put a credit note in your wallet, note the amount, expiry date and retailer on your phone, with a reminder two weeks before it expires. A credit note is lost more often through forgetfulness than bankruptcy — and in practice, it is better to give yourself a few weeks to find a piece worth the detour.
What if the shutters are already down?
One step remains, often futile, always possible: when a formal insolvency process is opened, credit-note holders are among the creditors and can submit their claim to the appointed insolvency practitioner, within the deadlines set out in the statutory notice. Do the cold maths: a few tens of pounds to declare, a process to follow, and a repayment that is often nil or token. If the amount is modest, your energy is better spent elsewhere.
Then there is the resale market, where you sometimes see credit notes sold on before a closure. Know this: a credit note is resold, when it is resold at all, below its face value, and the small print saying 'valid for one year' puts buyers off. A £100 credit note is not worth £100 in cash, for you or anyone else.
The habit worth keeping
A credit note is not a banknote: it is a promise with a date and a weak spot. Use it in the weeks after you get it, not some time in the coming year. Turn one down when a refund is offered, especially on a big piece. And if nothing tempts you right away, remember that a credit note converted into something you actually wear always beats an unused credit note from a retailer on the brink.
Your jeans too tight across the hips will not come back. The £35 might — provided you do not let it gather dust.
Comments
Your opinion matters: rate the article, react and reply to comments.
Comments are moderated; AI-assisted comments are flagged. Text emoticons (8-), :-), <3…) are automatically shown as images.